Mortgage Survey vs. Home Inspection: What’s the Difference?
A mortgage survey and a home inspection often get requested around the same time, which is exactly why so many buyers mix them up. One tells you where your property lines sit. The other tells you if the roof is about to fail. Confusing the two, or assuming one covers the other, can leave a real gap in what you know before closing. Here’s what each document actually does, and why your lender usually wants both.
Two Very Different Documents
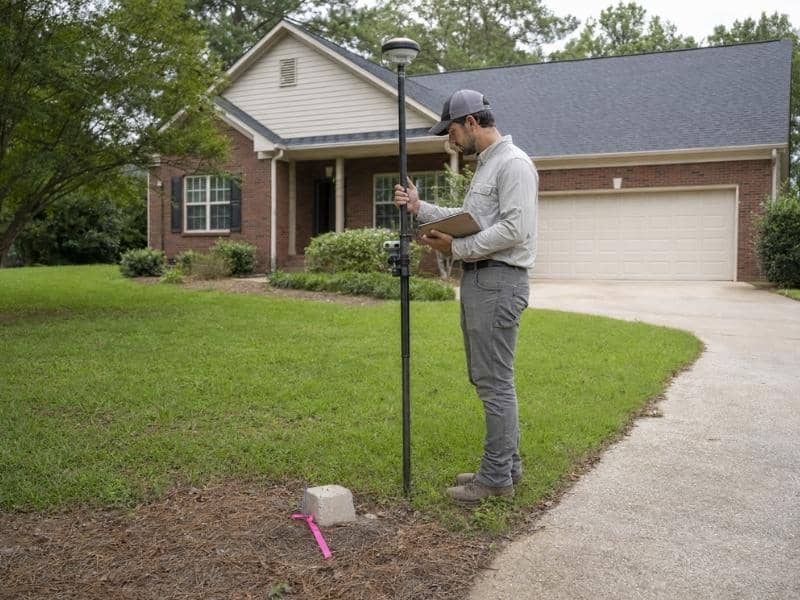
A mortgage survey is a land document. It shows the boundaries of the property, the location of structures on it, and whether anything on the site conflicts with the recorded deed. A home inspection is a building document. It looks at the physical condition of the structure itself, from the foundation to the wiring to the roof.
These two reports answer completely different questions. One asks “is this the land you think you’re buying.” The other asks “is this house in the condition you think it’s in.” Skipping either one leaves a blind spot that can cost real money later.
What a Mortgage Survey Actually Checks
Locating the Legal Boundary
A mortgage survey confirms where the legal property lines sit, based on the recorded deed and existing site conditions. This isn’t the same as a full boundary survey, which digs deeper into monuments and legal descriptions. A mortgage survey gives a lender enough confidence that the property matches what’s described in the loan paperwork.
This step matters because deeds and physical reality don’t always match perfectly. A garage might sit closer to the line than the paperwork suggests. A driveway might cross into a neighbor’s lot without anyone noticing for years.
Flagging Encroachments Before Closing
Part of the survey’s job is spotting anything that crosses the property line, whether that’s a fence, a shed, or part of a building. Lenders want this information before funding a loan, since an encroachment can affect the property’s value or create a future legal dispute.
Catching this before closing gives everyone a chance to resolve it. Waiting until after the sale is finalized makes the problem harder and more expensive to fix.
What a Home Inspection Actually Checks
A home inspection focuses entirely on the structure. An inspector walks through the property checking the roof, foundation, plumbing, electrical systems, HVAC, and general condition of the building. This report tells a buyer what repairs might be needed soon, and whether anything represents a safety concern.
None of this overlaps with what a survey does. An inspector isn’t measuring property lines, and a surveyor isn’t checking whether the water heater is about to fail. Each professional stays firmly in their own lane.
Why Lenders Ask for Both, Not One or the Other
Lenders want a complete picture before funding a loan. The survey protects them from lending against land that doesn’t match its legal description. The inspection protects the buyer, and indirectly the lender, from unknown structural problems that could affect the property’s long term value.
Some buyers assume one report makes the other unnecessary. That assumption creates real risk. A home could pass inspection with flying colors and still sit on a property with a serious boundary conflict. The reverse is also true, since a clean survey says nothing about whether the roof needs replacing.
Where Confusion Usually Starts
Part of the mix-up comes from timing. Both documents often get ordered around the same point in the closing process, so buyers sometimes assume they’re part of the same package. They’re prepared by completely different professionals using completely different methods, and neither one substitutes for the other.
Another source of confusion is the word “survey” itself, which gets used loosely in casual conversation. Some people use it to mean any kind of property check, blurring the line between what a surveyor does and what an inspector does. Knowing the difference helps you ask for the right service instead of assuming your inspection covers boundary questions it was never designed to answer.
What Happens If You Skip the Survey
Skipping a mortgage survey to save money can backfire. If a boundary issue surfaces after closing, resolving it becomes far more complicated once the sale is final. You might discover a structure encroaching on a neighbor’s land, or find that your own deed doesn’t match what’s actually on the ground.
Some lenders require a survey regardless, particularly for properties without a recent one on file. Even when it’s optional, skipping it to cut costs on a property purchase is rarely worth the risk it introduces.
Reading Two Reports at Once
When both documents land on your desk before closing, read them with their separate purposes in mind. The survey tells you about the land itself, including boundaries and any encroachments. The inspection tells you about the condition of what’s built on that land.
Ask questions about anything unclear in either report before you sign. A surveyor can explain a flagged encroachment. An inspector can walk you through a repair estimate. Getting clarity from the right professional, on the right document, keeps you from missing something that matters simply because it landed in the wrong report.
